
The fastest brokerages run one checklist, branched by loan purpose, and one six-step workflow: collect, classify, validate, submit, archive. Skip the branching and you get repeated document chasing; skip a defined SLA and files stall for weeks with no owner.
Deploy this today:
- Build a loan-purpose–branched intake link (conventional, refinance, cash-out, FHA, VA, self-employed) and send it by SMS.
- Assign a 5-business-day SLA for the borrower's first document batch.
The checklist itself groups by document class:
- Identification: government-issued photo ID, front and back
- Income: pay stubs, W-2s or tax returns, employment letter
- Assets: bank statements, investment/retirement statements
- Liabilities: existing loan statements, credit card balances
- Credit: authorization for credit pull, explanation letters for derogatory items
- Property: purchase agreement, appraisal, insurance binder
- Legal / title: title commitment, survey, divorce decree if applicable
- E-sign & consent: disclosures, privacy consent, borrower communication consent
Key Takeaways
A loan-purpose–branched checklist paired with a six-step intake workflow eliminates repeat document requests and gets files to underwriting-ready status faster than a generic, one-size-fits-all list.
| Point | Details |
|---|---|
| Branch by loan purpose | Separate checklists for conventional, refinance, cash-out, FHA, VA, and self-employed cut second-request rates sharply. |
| Set SLAs at every handoff | Use 24 hours for the initial request, 5 business days for borrower uploads, and 2 business days for validation. |
| Validate before it reaches underwriting | Check dates, name matches, and income math on every document class before advancing the file. |
| Log everything for audit | Timestamp uploads, signatures, and borrower messages so compliance reviews go smoothly. |
| Automate the highest-effort steps | Autowrite automates checklist branching, upload validation, and LOS population so your team spends less time chasing files. |
Table of Contents
- Mortgage Document Checklist by Loan Purpose
- What Is the Six-Step Intake Workflow?
- How Do You Spot Red Flags in Borrower Documents?
- File Naming, Formats, and Metadata Rules
- Compliance, Consent, and Audit Trail Basics
- Where Document Intelligence Actually Helps
- How Do You Handle Missing or Stale Documents?
- Best Practices for E-Signature Capture
- Disaster Recovery for Mortgage Document Storage
- Troubleshooting Digital Document Submission Problems
- Automate the Checklist Instead of Chasing It
- Frequently Asked Questions
- Sources
Mortgage Document Checklist by Loan Purpose
A single generic list is where most intake breaks down. Borrowers get one email listing "income documents" with no specifics, upload the wrong year's tax return, and the file bounces back for a second request. A loan-purpose–branched checklist cuts that second-request rate from roughly 38% down to under 12%, since the borrower only sees the items that actually apply to their file.
The table below reflects what a standardized checklist template should specify for each document class, including acceptable version windows and where loan purpose changes the requirement.
| Document Class | Required Items | Acceptable Version / Date Range | Loan-Purpose Variation |
|---|---|---|---|
| Identification | Government photo ID | Current, unexpired | VA files also require a valid Certificate of Eligibility |
| Income | W-2s or tax returns; pay stubs | Last 2 years tax filings; pay stubs from most recent dates | Self-employed borrowers need 2 years of full tax returns plus a YTD profit and loss statement |
| Assets | Bank and investment statements | Most recent bank statement pages | Cash-out refinances need proof of source for any large deposits |
| Liabilities | Loan and credit statements | Current statement, most recent cycle | Refinances require the current mortgage statement showing payoff balance |
| Credit | Signed credit authorization | Dated within an acceptable recent window | FHA and VA files may need letters of explanation for late payments |
| Property | Purchase agreement, appraisal | Fully executed, current | Purchases only; refinances substitute the current appraisal or AVM |
| Legal / title | Title commitment, survey | Issued within the lender's required window | Required on purchases and cash-out; often waived on rate-and-term refinances |
| E-sign & consent | Disclosures, consent forms | Signed at or before document request completion | Same across all loan purposes |
A borrower whose refinance file needs their current mortgage statement for payoff calculations is a good example of where generic checklists fail; a partner resource like HAUS's financing guidance walks through exactly which statements a refinance applicant typically needs to gather, which is a useful cross-check when you're building your own template.
Every uploaded file also needs three things attached automatically, not chased down later: uploader identity, an upload timestamp, and a file-type tag. PDF is the preferred format for anything the borrower didn't photograph on a phone; JPEG or PNG is fine for mobile captures as long as your intake tool can flatten them into a searchable PDF afterward. Cap individual uploads at 15MB and ask for scanned documents at 200 to 300 DPI so OCR extraction actually works instead of returning garbage text.
Build the template once per loan type and duplicate it rather than editing a master list on the fly. A downloadable checklist template, formatted as an editable spreadsheet or PDF, saves your processors from rebuilding the same structure every time a new loan purpose comes through the pipeline. Keep one master version control document so nobody is working from last year's FHA requirements.
What Is the Six-Step Intake Workflow?
Six triggers move a file from lead to submission, each with an expected output your team can check against.
- Lead capture → borrower enters the pipeline; automated action: CRM record created; output: contact and loan-purpose tag set.
- Application (1003) submitted → automated action: disclosure package queued; output: TRID clock started.
- Document request sent → automated action: loan-purpose–branched checklist delivered by SMS link; output: borrower has one clear list, not a scattered email thread.
- Document validation → automated action: AI checks file type, date range, and legibility; output: flagged items routed to a human for judgment calls.
- Disclosures & signatures → automated action: e-sign envelope sent and tracked; output: signed, timestamped disclosure set.
- LOS population & file submission → automated action: extracted data pushed into loan origination fields; output: underwriter-ready file.
Assign clear ownership. The loan officer owns lead capture and application intake. The broker assistant or coordinator owns the document request and follow-up reminders. The processor owns validation and LOS population. An underwriter liaison handles anything flagged for escalation. Set SLA targets at each handoff: approximately one day to send the initial document request after application, a few business days for the borrower's primary upload batch, and a couple of days for your team to validate what comes in.
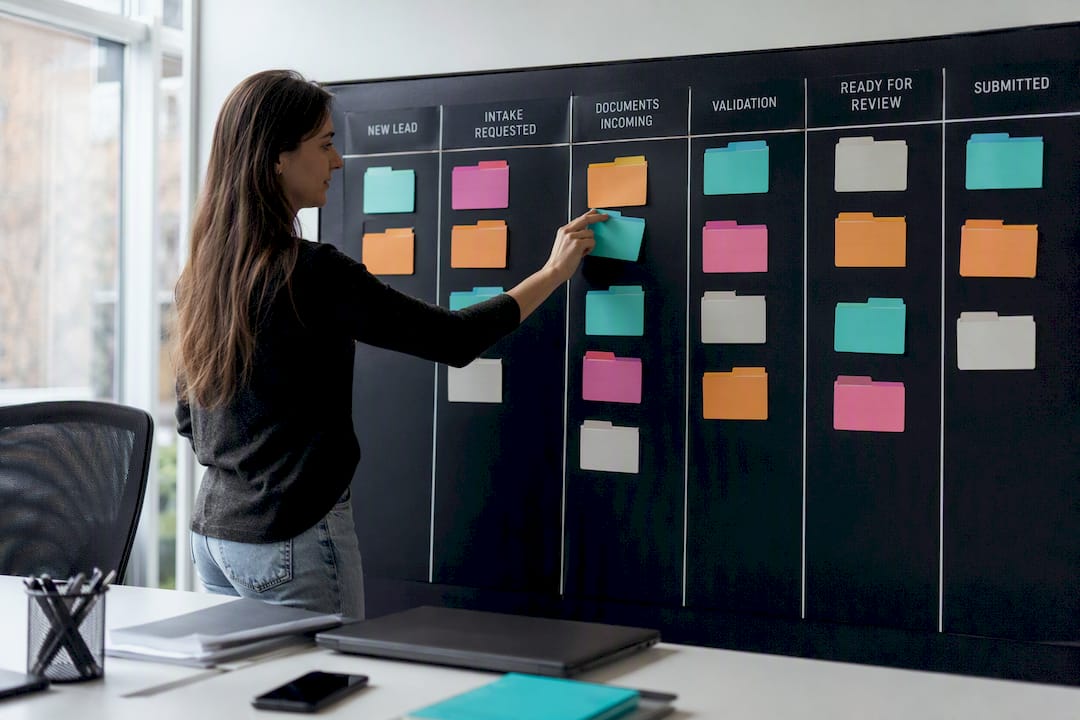
A simple Kanban board makes bottlenecks visible: New Lead, Intake Requested, Documents Incoming, Validation, Ready for Review, Submitted. A file only moves right when its exit condition is met. Documents Incoming only advances to Validation once every checklist item shows a green check, not "mostly there."
How Do You Spot Red Flags in Borrower Documents?
Validation is where sloppy intake turns into a compliance problem later. Check each document type on its own terms: IDs need both front and back and must be unexpired; W-2s need to match the tax year requested; pay stubs need year-to-date totals that actually add up against the stated pay rate; bank statements need a running balance that reconciles page to page; gift letters need a signature and a source account that matches the deposit.
Watch for these red flags and act immediately:
- Documents older than the acceptable window (stale pay stubs, an expired ID)
- Mismatched names or Social Security numbers across documents
- Income that can't be verified against stated employment
- Sudden, unexplained deposit spikes in bank statements
- Disclosures that were never signed
- Image metadata showing signs of editing
When any of these appear, escalate within 24 hours. Notify the underwriter liaison or compliance lead directly, attach the flagged document plus a one-paragraph summary of the inconsistency, and hold the file in Validation on your board rather than letting it advance quietly.
File Naming, Formats, and Metadata Rules
Consistent naming saves a processor from opening six files to find one pay stub. Use a pattern like BorrowerLast_First_DocType_YYYYMMDD_version, for example: Smith_John_PayStub_20260214_v1.pdf, Ramirez_Ana_BankStatement_20260201_v2.pdf, or Chen_Wei_W2_20250115_v1.pdf.
- PDF is preferred; JPEG or PNG is acceptable for mobile captures if converted to PDF/A on intake
- Cap uploads at 15MB per file
- Every upload needs metadata: uploader identity, timestamp, original filename, loan ID, loan-purpose tag
That metadata is what makes an audit trail defensible instead of a guessing game months later.
Compliance, Consent, and Audit Trail Basics
Every intake needs documented consent before you touch a credit file or send borrower communications: explicit authorization for the credit pull, e-signature capture on disclosures, and a record that the borrower agreed to be contacted by text or email. Skipping any one of these turns a routine file into a compliance exposure.
Your audit trail should log every meaningful event with a timestamp: document upload, signature completion, and every borrower-facing message sent from your team. Tamper-evident signature events matter more than most brokers assume during an audit.
A file with a complete, timestamped history of every upload and every message sent to the borrower survives a compliance review without a single follow-up question. A file missing that history invites one.
Retention windows vary by regulator and file type, so confirm yours with your compliance officer rather than assuming a blanket number. Store everything with encrypted, access-logged storage, and keep an offsite or cloud backup that's tested, not just assumed to work.
Where Document Intelligence Actually Helps
Automation earns its keep on the repetitive steps, not the judgment calls. The highest-impact candidates are loan-purpose branching for document requests, disclosure delivery triggered the moment an application lands, AI checks on upload for file type and date range, and automatic LOS population once disclosures are signed. AI should structure and flag, not decide eligibility; a human still makes the underwriting call.
A practical automation checklist:
- Trigger
form.submitted→ create CRM contact and send the branched checklist link - Trigger
applicationReceived→ fire disclosure package within 24 hours - Trigger
envelope.completed→ push data into LOS fields automatically - Confirm integrations exist for your intake form, CRM, LOS, and e-sign tool before going live
- Test each trigger on one sample file before rolling it out to the full pipeline
Pro Tip: Automate the three steps eating the most staff hours first: document checklist and follow-up, disclosure delivery, and LOS data entry. Pilot on a single loan type before expanding to the rest of your pipeline.
How Do You Handle Missing or Stale Documents?
A file with three missing items and one expired pay stub isn't a failure of your checklist, it's a normal Tuesday. What matters is how fast you re-collect.
The moment validation flags a gap, send a targeted reminder naming the exact missing item, not a generic "please upload your documents" nudge. Borrowers respond faster to specificity. If a pay stub or bank statement has aged past its acceptable window while the file sat in review, request a refreshed copy immediately rather than waiting until the underwriter kicks it back, since that second round-trip is what actually kills turnaround time.
Set a re-collection SLA that mirrors your original intake SLA: 3 business days for a single missing item, 5 for multiple items. If a borrower goes silent past that window, escalate to the loan officer for a personal follow-up call rather than another automated text. Partial files should never sit in Validation indefinitely; either move them back to Documents Incoming with a flagged reason, or escalate to the coordinator if the borrower has gone unresponsive for more than 7 business days.
Track how often files stall for the same reason. If tax transcripts are consistently the slowest item, that's a signal to request them earlier in the process, not a coincidence worth ignoring.
Best Practices for E-Signature Capture
E-signature isn't just a convenience feature. It's the audit trail your compliance officer will ask for if a disclosure timeline ever gets questioned.
Send disclosure packages through an e-sign envelope, not a PDF attached to an email, so every action carries a timestamp: sent, opened, signed. Confirm the envelope captures the signer's identity through a verification step, whether that's a knowledge-based question or an SMS code, especially for high-value disclosures like the initial Loan Estimate.
Never let a signed envelope sit unprocessed. The moment an envelope.completed event fires, that should trigger LOS population automatically rather than waiting for a processor to notice it in their inbox. That single trigger is one of the cleanest automation wins in the entire workflow.
Store the completed, tamper-evident certificate alongside the document itself, not in a separate system nobody checks. If a regulator or auditor ever asks whether a borrower actually saw a specific disclosure, that certificate is the answer, and it needs to be retrievable in under a minute, not after a scramble through old email folders.
Disaster Recovery for Mortgage Document Storage
Every brokerage assumes its document storage is safe until the day a sync fails or an account gets locked out mid-closing. Plan for that day before it happens.
Keep documents in a system with automated, tested backups, not a folder structure that depends on one person's laptop. Confirm your storage provider maintains geographically separate backup copies, and ask specifically how often backups are tested for restoration, not just how often they're taken. A backup nobody has ever restored from is a backup you don't actually have.
Set a recovery time objective your team can live with. For an active pipeline, that means files need to be restorable within hours, not days, since a closing date doesn't move just because a server did. Document who owns disaster recovery response internally so it's not being figured out for the first time during an actual outage.
Data residency matters too if your storage provider operates across borders; confirm where your borrowers' documents physically live and whether that matches your regulatory obligations.
Troubleshooting Digital Document Submission Problems
Most submission failures trace back to one of four causes: file size, file format, connectivity, or borrower confusion about which link to use.
If a borrower reports an upload failing repeatedly, check file size first; a 25MB scan from a home printer is a common culprit against a 15MB cap. Formats corrupted in transit, usually a HEIC photo from an iPhone that never converted properly, are the second most common issue. Ask the borrower to retry from a different browser or switch from WiFi to mobile data before assuming the platform itself is broken.
When a borrower says they never received their portal link, check delivery logs before resending; a link routed to a landline instead of a mobile number, or an email caught in a spam filter, causes more "missing" documents than anything else. Confirm the correct number or address in your CRM before sending a second link, or you'll create the exact duplicate-link confusion that stalls files.
If validation flags a document as unreadable, the fix usually isn't asking for a new copy immediately. Ask the borrower to rescan at a higher resolution first; a blurry phone photo of a bank statement is fixable without a full re-request.
First-person perspective: implementing this in a busy brokerage
Start small. One loan-type template, one SMS link per borrower, and reminders that name the exact missing item, not "your file needs attention," turn a stalled refinance into a ready-for-review file within days once the checklist and one automation rule are in place. Get manager sign-off on a two-week pilot, measure first-pass-complete rate, then expand.
Automate the Checklist Instead of Chasing It
Everything in this checklist works whether you run it manually or automate it, but manual tracking has a ceiling. Every added loan file means another spreadsheet row, another reminder someone has to remember to send, another chance a stale pay stub slips through. Autowrite runs this exact workflow, loan-purpose branching, AI validation on upload, e-sign integration, and LOS population, without a coordinator manually checking each box.
If you'd rather build this yourself first, pilot one loan type, confirm your field mapping into your LOS matches what your underwriters expect, then expand from there. If you'd rather skip the build entirely, Autowrite's platform already handles document classification, checklist branching, and compliance packaging for Canadian brokers, and you can start a trial without committing to a long-term contract.
Frequently Asked Questions
What should a mortgage document checklist include at minimum? It needs eight document classes covered: identification, income, assets, liabilities, credit authorization, property documents, legal or title items, and e-sign consent, each with a defined acceptable date range.
How long should brokers give borrowers to upload documents? A 5-business-day SLA for the first batch of primary documents is a reasonable standard, with a shorter 3-day window for re-collecting a single missing or stale item.
Should brokers use one document link or send separate requests? One borrower-specific link, delivered by SMS, consistently performs better than scattered email requests because it centralizes everything the borrower needs in one place.
What triggers should be automated first in the intake process? Document checklist delivery and follow-up, disclosure delivery within 24 hours of application, and LOS population after signed disclosures deliver the fastest return.
How do brokers know if their intake process is actually working? Track first-pass-complete rate, average time from request to full file, and second-request frequency; a rising second-request rate usually means the checklist isn't specific enough to the loan type.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Slash Mortgage Client Intake Time in 2026 (Examples + Templates) | US Tech Automations